Receiving a year-end bonus and 13th month pay brings welcome financial relief. After months of hard work, the extra money can help pay for holiday expenses, support loved ones, or fund personal goals. But beyond shopping and celebrations, this additional income can also be an opportunity to build financial security to last your whole life.
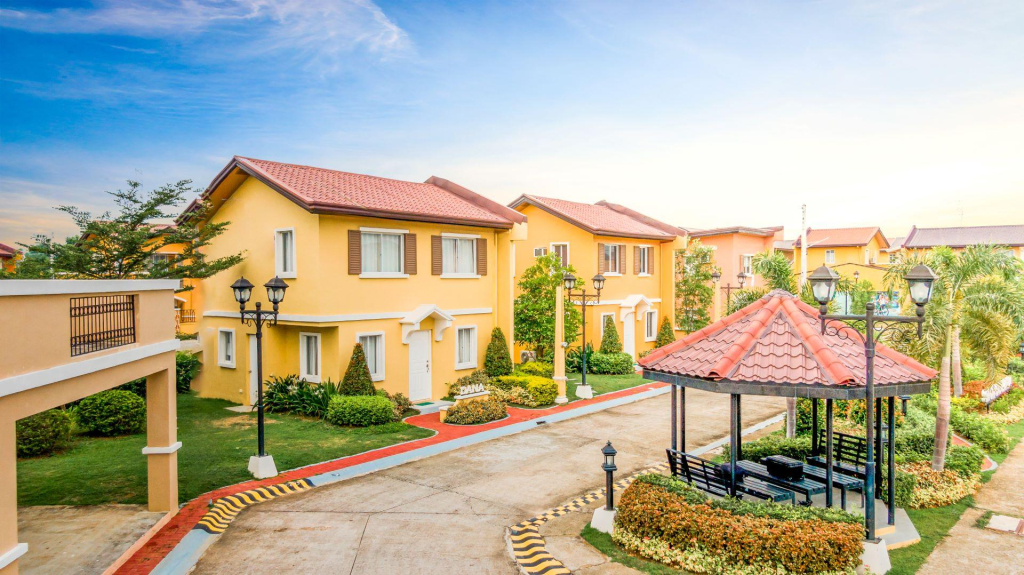
One smart way to use your year-end bonus is to put it toward a major investment, such as a home. For potential buyers who want a more immediate path to homeownership, a ready-for-occupancy (RFO) property is worth considering. Unlike a pre-selling property, an RFO property is already built and can offer a clearer picture of what you are buying, when you can move in, and how the property fits your needs.
Why an RFO Property Investment Could Be the Right Move
Before spending your bonus, here’s how to assess whether buying an RFO property is the right move for your finances and future wealth.
1. Turn Your Year-End Bonus Into a Long-Term Asset
It can be tempting to spend your entire year-end bonus on gifts, travel, gadgets, or maybe a new car or a lifestyle upgrade. While enjoying the rewards of your hard work is important, here’s another great idea: You can also set aside a portion for a long-term goal to make your money work harder for you.
A property can become a valuable asset over time, depending on its location, condition, demand, and broader market conditions. Rather than treating your bonus as extra spending money, consider using part of it for a down payment, transaction costs, or other expenses associated with buying a home.
However, buying property should not come at the expense of your financial protection. Before committing, make sure you have sufficient money for daily expenses, an emergency fund, insurance, and outstanding debt payments. Your savings should support your purchase, not leave you financially stretched.
A secure and practical approach is to divide your bonus according to your priorities. Set aside money for essential expenses first, allocate some for savings and debt repayment, and determine how much you can comfortably put toward your property goal.
2. Why Consider an RFO Instead of a Pre-Selling Property?
Both RFO and pre-selling properties can suit different financial situations, but their timelines, benefits, and premiums differ.
An RFO property is already constructed and available for occupancy, subject to the developer’s turnover requirements and completion of the purchase process. This lets buyers inspect the actual house, condo, or unit and assess its layout, quality of finishes, and surroundings before making a decision.
A pre-selling property, on the other hand, is purchased while construction is in progress or before the development is ready for occupancy. It may come at a lower price than a comparable completed property and may offer flexible payment terms during construction. However, buyers generally need to wait for completion, and the final experience can differ from their initial expectations.
The main advantage of an RFO property is immediacy. If you need a home for your family soon, want to stop renting, or plan to relocate, a completed property may better match your timeline. You can evaluate the actual space and plan your move with greater clarity.
That convenience may come with a higher price compared with some pre-selling options. The best choice depends on your budget, preferred location, financial readiness, and how soon you need the property.
3. Make Your Bonus Work With a Realistic Budget
Your year-end bonus and 13th month pay can help you prepare for a property purchase, but they should be part of a larger financial strategy rather than your only source of funds.
Start by calculating the total cost of buying a property. Beyond the selling price, account for possible reservation fees, down payment, taxes, legal and documentation costs, loan-related charges, insurance, and moving expenses. Ask the developer or lender for a detailed breakdown of payment terms so you understand what is due upfront and what you will need to pay later.
Next, review your regular income and expenses. If you plan to finance your purchase through a bank, estimate your monthly amortization and consider how interest rates could affect your payments. Make sure you can cover the loan even when unexpected expenses arise or your income changes.
For example, if your bonus is enough to cover part of the down payment, avoid using every peso simply because it is available. Keep sufficient savings in your bank account to protect yourself against emergencies. A home should provide peace of mind, not become a source of constant financial stress.
Careful budgeting helps you see whether buying now is practical or whether you need more time to save.
4. Consider the Value of Moving Into a Completed Home
For potential buyers who currently rent, an RFO property can offer a more direct route toward having a place of their own. Instead of waiting for construction to finish, you may be able to move in once the required purchase and turnover steps are completed.
This can be useful for growing families, professionals changing jobs, or buyers who need a home in a particular location. Being able to see the actual property also makes it easier to evaluate room sizes, storage, natural light, and the surrounding community before making a commitment.
An RFO purchase may also suit buyers who want to use their property to generate rental income for a bit of extra cash. Since the unit is already built, you can assess its condition and local rental demand before deciding whether to lease it. Still, rental income is not guaranteed. Account for vacancies, maintenance, association dues where applicable, taxes, and other ownership costs before relying on rent to support your investment.
Ultimately, a property’s value depends on more than its completion status. Location, accessibility, nearby amenities, maintenance, and market demand prove that there are more factors in a property’s long-term appeal.
5. Protect Your Finances Before You Invest
A property purchase is a major financial commitment, so financial protection should remain a priority. Before signing a contract, review your current liabilities, including credit card balances, personal loans, and other monthly obligations. You first need to develop a great strategy. High-interest debt can limit the money available for your home and increase financial pressure.
Maintain and secure an emergency fund that can cover several months of essential living expenses, with the appropriate amount depending on your income stability and household needs. Keep insurance coverage suited to your circumstances, and avoid making a purchase based only on the excitement of receiving a bonus or marketing hype.
It’s also important to check the developer’s credentials, review the property’s legal documentation, understand the contract, and clarify what happens if you miss a payment. Ask questions about turnover conditions, warranties, and any additional fees before committing.
Taking time to verify these details can work to your advantage. This helps protect your savings and reduce the risk of an expensive mistake. If you’re unsure about financing or legal obligations, seek advice from a qualified financial or legal professional.
6. Build Your Future One Smart Decision at a Time
Using your year-end bonus for a home does not mean you can’t spend on a present-day reward. Financial planning is about finding a balance between enjoying your income now and building security for the future.
You might use part of your 13th month pay for a family celebration, invest in a new skill that supports personal growth, pay down debt, and save the rest toward a property. These goals can work together when you have a clear budget and realistic expectations.
The importance of a home goes beyond its price. A house can give your family a stable place to live, help you plan for future milestones, and provide a sense of security. Whether you choose an RFO property or a pre-selling home, the right purchase is one that supports your lifestyle without compromising your financial well-being.
Find Your Dream RFO Home With Camella
If you’re considering turning your year-end bonus into a meaningful investment, explore the RFO house-and-lot options available through Camella.
With communities in locations across the Philippines, Camella offers home options for buyers looking to find a space that suits their family’s needs and long-term plans.
Before making a purchase, compare available properties and their prices, ask about current inventory and payment terms, and calculate the full cost of ownership. Confirm which units are ready for occupancy, as availability can vary by community.
Your year-end bonus can be more than a reward for the work you’ve done. With careful planning, it can help you take a step toward a home of your own.
Visit Camella’s official website to discover its communities and inquire about available properties. Start planning today for a home that supports your loved ones’ future.